

Citi Mobile®

- 425.27K Reviews
- 4.8
- Downloads
- 10,000,000+
Our take on Citi Mobile® from Appgk
Managing a bank account from a phone sounds simple until you need to do something quickly, check a suspicious charge, or understand where your money went. I spent time using Citi Mobile® as a daily finance app, and my overall impression is that it works best when treated as a practical control panel rather than a complete replacement for every banking task. It puts routine account work within easy reach, while still leaving a few situations where the fuller web experience or direct help is more comfortable.
Developed by Citibank N.A., this free finance app is available for everyone and has built a very large audience: it has passed ten million installs, with an average rating of 4.8 from around 1.4 million ratings. Those figures suggest that it has become a familiar tool for Citi customers, but popularity alone does not tell me whether it fits a particular banking routine. The more useful question is how well it handles the small actions people repeat every week.
How I use Citi Mobile® for everyday banking
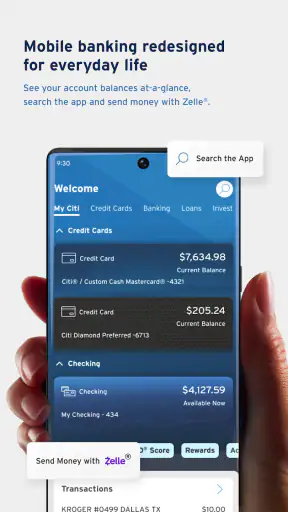
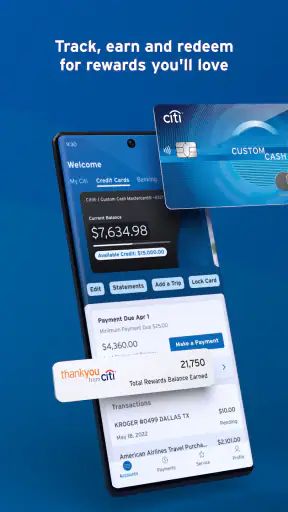
My basic workflow starts with opening the app to check balances and recent activity before making a payment or moving money. That sounds ordinary, but it is the foundation of a good mobile banking habit. Instead of waiting until a statement arrives, I can use short checks to notice an unfamiliar purchase, confirm that a payment went through, or see whether an expected deposit has appeared.
The store summary describes the app as a way to manage accounts virtually anytime and anywhere, and that matches its main strength. It is designed around access rather than financial education. I would not open it expecting a budgeting course or a detailed plan for improving my finances. I open it when I need a current view of my Citi accounts and want to act without sitting at a computer.
Best Parts of Citi Mobile®
Things to Keep in Mind About Citi Mobile®
A realistic example is paying a card balance during a lunch break. I can sign in, review the current amount, check recent transactions, and complete the payment without gathering paperwork. The important habit is to pause before confirming: I verify the account, amount, and payment details rather than treating mobile convenience as a reason to rush. That small check matters more than any shortcut.
The app is also useful when I am away from home and need to answer a practical question. If I am standing at a checkout, I may want to know whether a purchase has already posted or whether available funds look different from what I expected. A mobile banking app cannot remove every uncertainty, especially when transactions are still pending, but it gives me a much faster starting point than calling support for every ordinary question.
News and Features Related to Citi Mobile®

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
News
Moovit Review: A More Reliable Way to Navigate Everyday Transit
News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
I found the experience most comfortable for short sessions. The app encourages a rhythm of sign in, inspect, act, and leave. That is a better fit for checking an account before a transfer than for spending a long time analyzing months of financial history. People who prefer a large screen, printed records, or several browser tabs may still favor online banking for more involved work.
What the first setup should accomplish
When installing a finance app, I would not begin by exploring every screen. I would first make sure I can sign in reliably, recognize the accounts shown, and understand where the main actions live. This reduces friction later, particularly when I am using the app in a hurry. Citi Mobile® runs on devices using iOS 10 or later, so checking compatibility before installation is sensible if the phone is older.
Don't want to read the full review?
I also recommend taking a moment to learn the difference between a posted transaction and one that is still pending. That distinction can prevent a needless second payment or an incorrect assumption about available money. The app can show account activity, but the user still has to interpret timing carefully. A transaction appearing in the activity area is not automatically the same as money being fully settled.
Another useful first step is deciding what I actually want the app to do. For some users, the answer is simply balance checks and card payments. Others may need account transfers or transaction monitoring. Defining that routine keeps the app from becoming a place where I tap through screens without a clear purpose. In finance, fewer careless actions are often more valuable than more features.
Screenshots
Settings and habits worth checking
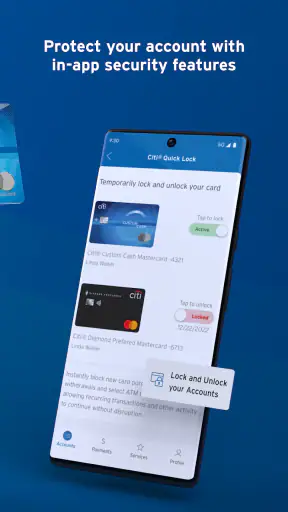
I pay attention to the app’s available sign-in and notification choices rather than accepting every default without thought. The right setup depends on the phone and the user’s comfort, but the principle is consistent: convenient access should not become careless access. I want a method that lets me get in efficiently while keeping the device itself protected with a lock screen and sensible privacy habits.
Notifications deserve a quick review because financial alerts can be useful and distracting at the same time. I prefer notifications that help me notice account activity or important changes, while avoiding a crowded stream that makes genuine warnings easier to ignore. I also consider who might see previews on the lock screen. A banking alert can reveal more than I want displayed in public, so the phone’s notification privacy settings are part of the banking setup.
One non-obvious habit is to review account activity at a consistent time instead of checking randomly whenever anxiety appears. A brief check after regular spending gives me a clearer baseline. If something looks unfamiliar, I can compare it with receipts and subscriptions while the details are still fresh. This is more useful than opening the app repeatedly without recording what I have already verified.
I also keep the app updated through the normal device store process. The current version is 9.97.0, and using the current release is generally preferable for compatibility and security maintenance. I do not treat an update as a reason to change every habit, though. After an update, I quickly confirm that the actions I use most—account viewing, payment review, and activity checking—are still easy to find.
Security is not just a setting inside the app. I avoid using a banking session on an unfamiliar shared device, and I am careful with messages that ask me to sign in through an unexpected route. If a notification or email creates urgency, I prefer opening the app directly rather than following a questionable prompt. The app can provide account access, but it cannot make a careless response to a scam safe.
Faster patterns for repeat tasks
Experienced use comes from reducing repeated decisions, not from tapping as quickly as possible. I keep a simple mental sequence for common jobs: open the correct account, check the latest activity, confirm the amount, and then complete the action. Repeating that order makes it less likely that I will pay from the wrong account or overlook a recent adjustment.
For regular payments, I check the due information and recent activity before submitting anything. This is especially important when I may have already scheduled or made a payment elsewhere. A fast workflow is only good if it prevents duplicate actions. I would rather spend a few extra seconds comparing the visible account details than save time and create a correction problem later.
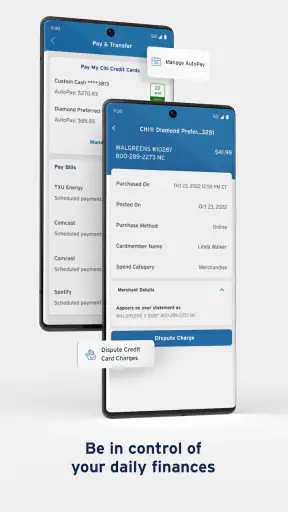
When investigating a purchase, I start with the transaction description and date, then compare it with my own records. Merchant names do not always look exactly like the name remembered from a shop or service, so I avoid treating an unfamiliar label as automatic fraud. At the same time, I do not dismiss a charge simply because the amount is small. The useful pattern is verify first, then take the appropriate next step through the bank’s available support or dispute process.
Another practical shortcut is keeping the phone’s home-screen arrangement organized around the apps I actually use. I place the banking app where I can reach it without searching, but I do not use that convenience as an excuse to leave the phone unlocked. The shortcut saves navigation time; the device lock protects the shortcut. That combination is more sensible than relying on either one alone.
I also avoid beginning a complicated task when I have only a few seconds. If I am about to board transport or enter a meeting, I may check a balance but postpone a larger transfer until I can review every confirmation screen calmly. Mobile access is valuable precisely because it is available in awkward moments, yet availability does not mean every moment is suitable for a high-consequence action.
Where the app is strong—and where it reaches its limits
The strongest part of Citi Mobile® is its role as a convenient front door to Citi accounts. It is a good match for customers who want routine access from a phone and prefer short, focused interactions. The fact that it is free removes a barrier for existing Citi customers deciding whether to install it, and its Everyone content rating makes it broadly approachable from an age-label perspective.
Its limitations are mostly about context. A phone screen is not ideal for comparing many transactions, studying long-term spending, or preparing detailed records. If I were reconciling several accounts, exporting information for a larger personal-finance system, or trying to understand a complicated financial picture, I would be more comfortable using a full browser interface or a dedicated budgeting tool where available.
This is also not the right choice for someone who does not bank with Citi. The app’s value comes from access to Citi relationships, not from acting as a neutral account aggregator or general-purpose money manager. A person who uses several unrelated banks may prefer a separate finance service that brings accounts together, accepting the trade-off that such a service may offer less direct control than the official app.
Compared with visiting a branch, the app is faster for routine checks and payments, and it avoids travel or waiting. Compared with calling customer service, it is more efficient for information already exposed in the account interface. But neither comparison means the app replaces human help in every case. A complex account issue, a concern about unauthorized activity, or a situation requiring explanation may still be better handled through official support.
I also would not judge the app solely by its high rating. A 4.8 average and around 425,000 written reviews show strong overall reception, but individual banking experiences can depend on the account type, device, sign-in situation, and task being attempted. A smooth balance check does not guarantee that every unusual request will feel equally straightforward. My recommendation is based on the app’s everyday usefulness, not on assuming that every user will have the same experience.
Who should use it and who should look elsewhere
I would recommend Citi Mobile® to an existing Citi customer who wants dependable phone access for balances, activity review, and ordinary account management. It is particularly suitable for someone who checks finances in small moments throughout the day and values an official channel over a third-party dashboard. The app’s large install base also means it is a well-established choice rather than an obscure experiment.
I would be more cautious about recommending it to someone whose main goal is deep budgeting. If the desired experience is category-based spending analysis, shared household planning, or a broad view across multiple institutions, a dedicated budgeting product may be a better fit. That does not make Citi Mobile® poor at banking; it means the app has a narrower and more practical center of gravity.
Users with older devices should confirm that the operating system meets the iOS 10 minimum before planning around it. People who dislike mobile authentication, small screens, or phone-based financial work may also prefer the web route. In my view, the best setup is not necessarily choosing one channel forever. I use the app for immediate checks and routine actions, while keeping a larger-screen option in mind for work that benefits from more space.
Parents and caregivers should also think about account responsibility rather than the Everyone label alone. An age rating describes general content suitability; it does not mean every banking action is appropriate for every person. Access should be arranged according to the account holder’s needs and the bank’s own requirements, with device privacy taken seriously.
My verdict after building a repeatable routine
After using Citi Mobile® as a working finance tool, I see its value in the quiet repetition of ordinary tasks. It helps me check what happened, confirm what needs attention, and complete straightforward actions without opening a computer. The best results come from combining the app with disciplined habits: review before paying, inspect notification privacy, keep the device protected, and slow down whenever an action has lasting consequences.
I would not call it a complete personal-finance system, and I would not choose it for someone seeking detailed budgeting across many banks. Its advantage is more focused: it gives Citi customers a convenient official place to manage accounts from a phone. That focus is a strength when my need is immediate account control, but a limitation when my goal is broader financial planning.
The app has been available since September 22, 2011, and its current release, 9.97.0, shows that it remains an actively maintained part of Citi’s mobile experience. I value that continuity, while still treating each update as a reason to check my familiar workflows rather than assuming nothing has changed.
My final recommendation is straightforward: if you already use Citi and want mobile access for everyday banking, install it and build a careful routine around the tasks you repeat most. The real benefit is not simply having a bank app on your phone; it is making account checks deliberate, quick, and safer. For broader budgeting, multi-bank visibility, or complex financial work, pair it with a more suitable tool instead of expecting one app to do everything.
Citi Mobile® FAQ
What is Citi Mobile® and what can I do with it?
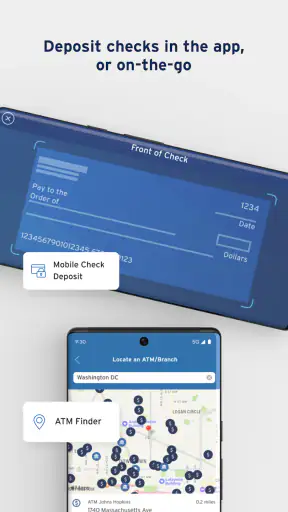
Citi Mobile® is Citi’s official mobile banking application for eligible customers. After signing in, you can typically review account balances and transactions, transfer money, pay bills, manage cards, deposit checks where supported, receive alerts, and locate ATMs or branches. Available tools can differ by country, account type, and Citi service, so the features shown in the app may not be identical for every user.
Is Citi Mobile® safe to use for banking and card management?
Citi Mobile® includes security features designed to protect access to your financial information, such as encrypted connections, login verification, biometric authentication on compatible devices, and transaction alerts. However, no banking app replaces safe user habits. Download it only from an official app store, keep your phone and operating system updated, avoid public Wi-Fi for sensitive actions, and never share passwords or one-time verification codes.
Do I need a Citi account to use Citi Mobile®?
Yes, most of the app’s banking and card-management functions require an eligible Citi account and valid online banking credentials. New customers may be able to apply for selected Citi products through the app or be directed to Citi’s website, depending on their location. Registration, supported account types, and access requirements vary by market, so check the official Citi information for your country before downloading.
Can I deposit checks, transfer money, and pay bills with Citi Mobile®?
In supported regions and for eligible accounts, Citi Mobile® may let you deposit checks using your phone’s camera, move money between accounts, send transfers, and schedule or make bill payments. Limits, processing times, fees, recipient eligibility, and availability can vary. Before confirming a transaction, carefully review the destination account, amount, date, and any applicable disclosures displayed in the app.
What should I do if Citi Mobile® does not work or I lose access to my account?
If the app crashes, fails to load, or rejects a login, first check your internet connection, update the application, restart your device, and make sure your phone’s operating system is supported. Avoid repeatedly entering uncertain credentials, as this may lock access. Use Citi’s official support channels or the recovery options shown on the sign-in screen, and contact Citi immediately if you notice suspicious activity.











